How to Budget When You Hate Math (Real-Life Tricks That Work)
If the word “budget” makes you want to close the laptop and pretend bills don’t exist, you’re not alone. A lot of budgeting advice assumes you love spreadsheets, enjoy calculating percentages, and want to track every penny down to the cent. That’s just not how most brains work, and it’s definitely not how yours has to work.
The good news is that budgeting isn’t actually about math. It’s about awareness and a few simple systems that run on autopilot once you set them up. You don’t need a formula. You need a method that fits how you naturally think, and that’s exactly what we’re covering here.
Why Traditional Budgeting Feels So Hard
Most budgeting templates were built by people who genuinely enjoy numbers. They’re full of columns, percentages, and formulas that update automatically, which sounds great until you’re the one who has to fill them in every week.
If you’ve tried one of those spreadsheets and abandoned it within a month, that’s not a failure on your part. It just means the tool didn’t match how you process information. Some people think in numbers. A lot of people think in categories, visuals, or simple yes-or-no decisions, and budgeting can absolutely work that way too.
The goal isn’t to become a numbers person. The goal is to find a system that keeps you aware of where your money is going without requiring mental math every time you open your wallet.
Start With Awareness, Not a Formula
Before you pick any budgeting method, spend a week just noticing your spending without judging it. Every time you buy something, jot it down in your phone’s notes app or a small notebook you keep in your bag.
You’re not calculating anything yet. You’re just building a factual picture of where your money actually goes, which is usually pretty different from where you think it goes.
At the end of the week, sort what you wrote into a few broad categories, like:
- Needs: Groceries, gas, bills, and anything that keeps the household running.
- Wants: Takeout, streaming subscriptions, that candle you didn’t need.
- Surprises: The birthday gift you forgot about, the copay, the car repair.
This exercise alone tends to shift how people spend, simply because they’re paying attention. No formulas required.
Try the Envelope Method (Digital or Physical)
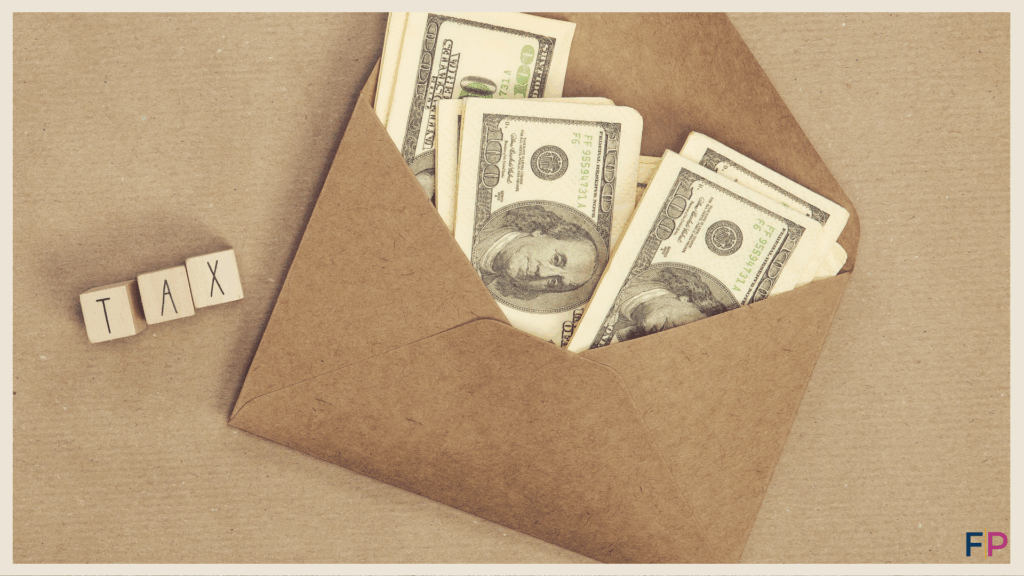
The envelope system has been around for decades because it turns budgeting into something visual and physical instead of something abstract. You take your spending categories and assign each one an envelope with a set amount of cash inside.
Once an envelope is empty, that category is done for the month. There’s no mental math involved because the limit is right there in your hand. If you’d rather skip cash entirely, most banking apps now offer digital envelope or “bucket” features that work the same way without the trip to the ATM.
This method works especially well for categories that tend to sneak up on you, like eating out, entertainment, or clothing. Seeing the cash (or the digital balance) shrink is a much stronger signal than trying to remember a percentage in your head.
Use the 50/30/20 Rule as a Rough Guide, Not a Rulebook
You may have heard of the 50/30/20 approach, where 50% of your income goes to needs, 30% to wants, and 20% to savings. If percentages make your eyes glaze over, here’s a shortcut: skip the math and think in thirds instead.
Roughly half your paycheck covers the essentials. A little less than a third is yours to enjoy without guilt. The rest goes toward savings or debt payoff. You don’t need to calculate exact percentages to apply this. You just need a rough sense of proportion, which most people can eyeball once they know their categories.
If your income is irregular or your needs eat up more than half, that’s fine too. The point isn’t to hit an exact number. It’s to have a general shape to check your spending against.
Automate Everything You Can
The single best trick for people who hate math is to remove the math from your daily life entirely. Set up automatic transfers so that savings, bill payments, and debt payments happen the moment your paycheck lands, before you ever have to think about it.
Here’s what that can look like in practice:
- Automatic savings transfer: A set dollar amount moves to savings the day you get paid.
- Autopay for fixed bills: Rent, utilities, and subscriptions get paid without you lifting a finger.
- A separate spending account: Whatever’s left after the above goes into an account you use freely, guilt-free.
Once this is set up, your budget essentially runs itself. You’re not calculating anything week to week. You’re just checking the leftover amount in your spending account before you buy something.
Round Numbers Are Your Friend
You don’t need to know your grocery budget is $347.82. You need to know it’s “around $350,” and that’s genuinely close enough. Rounding to friendly numbers makes budgeting feel less like accounting and more like general planning, which is a much easier mental load to carry.
This works for almost every part of budgeting. Round your bills up to the nearest ten. Round your paycheck down to a number that’s easy to work with. The small cushion this creates also tends to work in your favor, since you’ll usually have a little more than you planned rather than less.
Pick a “Money Day” Instead of Tracking Constantly
Instead of thinking about your budget every time you make a purchase, choose one consistent day to handle all your money tasks at once. Pay bills, move money into savings, and glance at your account balances, then close the laptop and don’t think about it again until next time.
This works because it turns budgeting into a single, contained task rather than a background worry that follows you around all week. Pick a day that lines up with your pay schedule, whether that’s payday itself or the day after, so the timing feels natural instead of forced.
Over time, this rhythm becomes a habit the same way laundry day or grocery day does. You stop needing to remember to check your budget because you already know when that happens.
Give Every Dollar a Job (Without the Spreadsheet)
Zero-based budgeting has a reputation for being detailed and number-heavy, but the underlying idea is simple: every dollar you earn gets assigned a purpose before you spend it. That doesn’t require a spreadsheet.
You can do this with sticky notes, a simple list in your phone, or even separate savings accounts labeled by purpose. The point is that nothing sits around unassigned, waiting to get spent on something random. When money has a job, you’re less likely to wonder where it went.
Use Cash for Your Trickiest Category
If there’s one spending category that consistently blows past whatever limit you set, whether that’s dining out, hobby supplies, or impulse buys at the store, consider pulling that one category out and running it entirely on cash.
Withdraw the amount you’ve decided on at the start of the month or week, and once it’s gone, it’s gone. There’s no app to check, no balance to calculate, just a physical stack of bills that gets thinner as the month goes on. Most people find this far more effective than watching a digital number tick down, since cash has a way of feeling more “real” than numbers on a screen.
You don’t need to run your entire budget on cash for this to work. Isolating just the one problem category is often enough to bring it back under control without overhauling everything else.
Check In Weekly, Not Daily
Checking your spending every single day is exhausting and tends to backfire, especially if numbers already stress you out. A better rhythm is a short weekly check-in, maybe ten minutes on a Sunday, where you glance at your accounts and ask yourself two questions:
Did anything unexpected come up this week? Are your envelopes or spending categories still on track? That’s it. You’re not recalculating your whole budget. You’re just staying aware, which is really all budgeting requires.
Use Visual Tools Instead of Numbers
If numbers on a page don’t mean much to you, try translating your budget into something visual instead. A simple bar that fills in as you spend, color-coded categories, or even a jar system for savings goals can make your budget click in a way that columns of numbers never will.
Many banking apps already build this in, showing your spending as bars or pie charts rather than raw figures. If yours doesn’t, a basic printable tracker with fill-in bars can do the same job for free.
Let Go of Perfection
One of the biggest reasons budgets fail isn’t math. It’s the pressure to do it perfectly, down to the last cent, every single month. Real budgeting has some wiggle room built in, and that’s not a flaw in the system. That’s what makes it sustainable.
If you overspend in one category, borrow from another. If a month goes sideways because of an unexpected expense, adjust and move forward instead of scrapping the whole system. A budget you can stick with imperfectly beats a perfect budget you abandon after two weeks.
The Bottom Line
Budgeting doesn’t require a head for numbers. It requires a system that matches how you naturally think, whether that’s visual, physical, or fully automated. Pick one or two of these tricks to start with rather than trying to overhaul everything at once, and give yourself permission to adjust as you go.
Once your system runs quietly in the background, you’ll find yourself thinking about money less, not more, which is really the whole point.